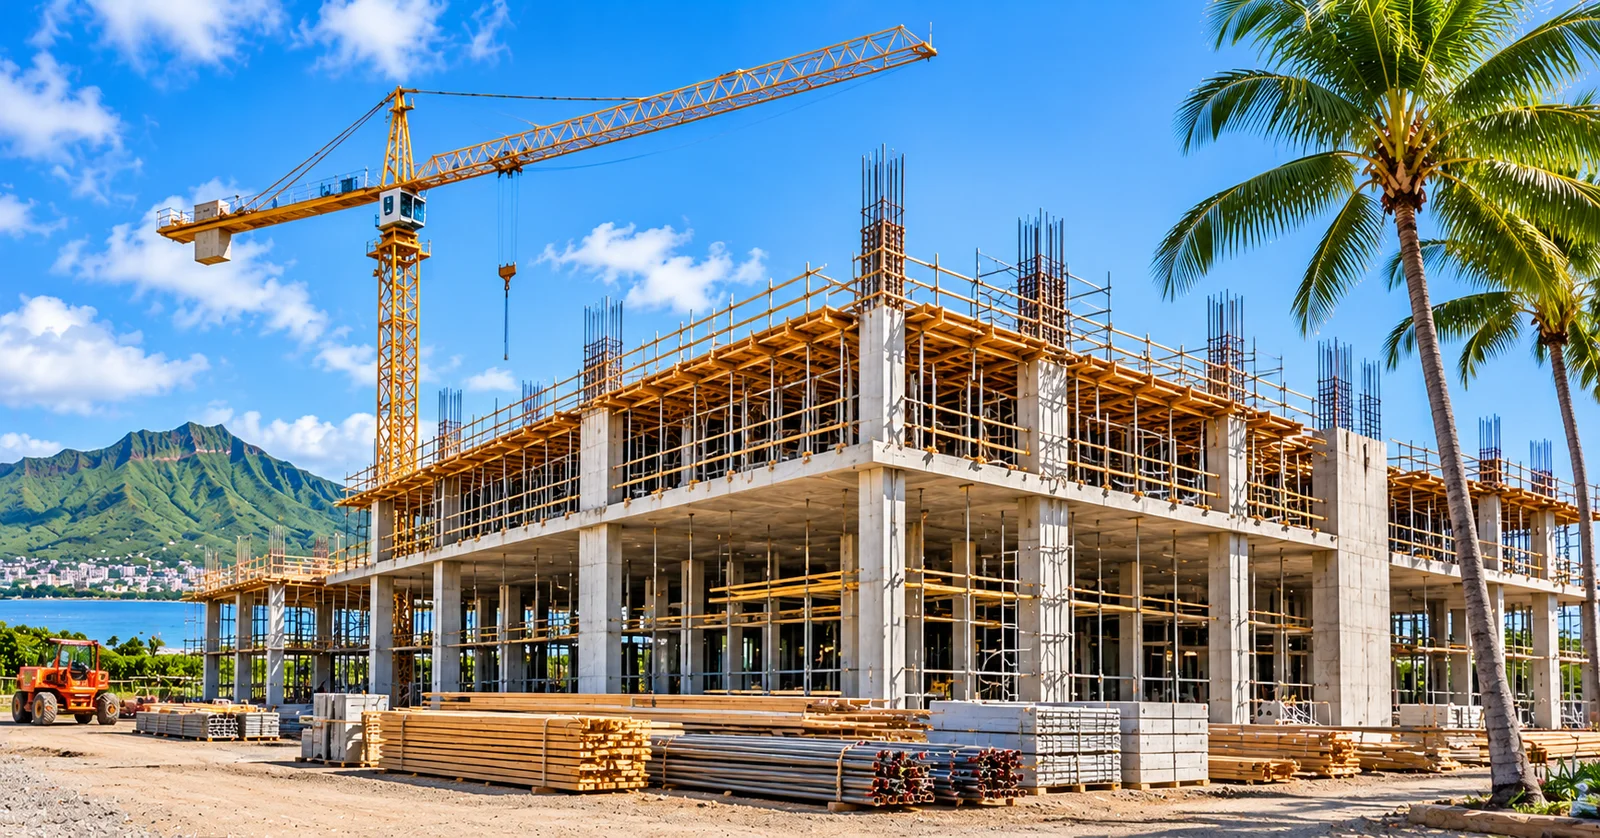
Finance new commercial development with construction loans structured around your project budget, timeline, and exit strategy. We work with investors and developers to evaluate project feasibility and structure financing for eligible ground-up construction projects.
Ground-up construction requires financing that accounts for more than the property's current value. Project budgets, permitting, construction schedules, builder experience, and the plan for repayment all play important roles.
Myers Capital Hawaii evaluates these factors to structure construction financing around the project's scope, capital requirements, and anticipated completion timeline.
Whether you're developing a new commercial property or advancing a project with plans and approvals in place, our direct lending approach provides a flexible financing option for eligible development opportunities.
PROGRAM DETAILS
Construction Financing Structured Around Your Project
No Personal Income Verification
Available for qualifying transactions.
Maximum Loan-to-Cost (LTC)
Up to 80%.
Acquisitions
Up to 80% Loan-to-Value (LTV), where applicable.
Refinances
Up to 65% Loan-to-Value (LTV), where applicable.
Loan Amounts
$250,000 to $10 million.
Loan Terms
12 to 36 months, with extensions possible.
Fast Closing
As little as two weeks for qualifying transactions.
Credit Flexibility
FICO scores as low as the mid-500s for eligible borrowers.
Project-Based Underwriting
Evaluation of development plans, budgets, timelines, and overall feasibility.
Construction Cost Financing
Financing structured around eligible construction costs and project requirements.
Land Acquisition
Potential financing for land acquisition as part of an eligible development transaction.
Staged Funding
Construction draws coordinated with project progress and applicable funding requirements.
Flexible Loan Structures
Financing evaluated based on the project, borrower experience, and proposed exit strategy.
Direct Lender Communication
Work directly with our team to discuss project requirements and financing structure.
Nationwide Lending
Available in eligible markets across our 42-state footprint.
Actual loan amounts, leverage, terms, credit requirements, closing timelines, construction draws, and eligibility depend on the project, market, underwriting, and program guidelines.
PROPERTY TYPES
Eligible Commercial Property Types
We consider financing for eligible commercial development projects involving:
✓Multifamily
✓Mixed-Use
✓Industrial
✓Retail
✓Hospitality
✓Land
✓Leasehold — Hawaii only
Property and project eligibility varies by program and market.
Share the project location, development plans, estimated budget, funding requirements, and anticipated completion timeline.
02
Submit Project Documentation
Provide available plans, permits, construction budget, builder information, and other supporting documentation.
03
Underwriting and Loan Structure
Our team reviews project feasibility, construction costs, borrower experience, funding requirements, and the proposed exit strategy.
04
Closing and Construction Funding
Once underwriting and closing requirements are satisfied, financing is finalized. Construction funds are disbursed according to the approved draw schedule and applicable requirements.
CONSTRUCTION FINANCING CASE STUDIES
Financing Real Estate Projects with Complex Requirements
Every development project has its own budget, timeline, and capital requirements. Our team evaluates each opportunity to determine whether it fits our lending parameters.
Single-Family Home & ADU$1,150,000BRIDGE LOAN WITH CONSTRUCTION HOLDBACK
Honolulu, Oahu, Hawaii
A cash-out bridge loan with a $400,000 construction holdback supported ground-up construction of a new single-family home and ADU. The financing included a nine-month interest reserve, with repayment planned through refinancing.
Mixed-Use & Residential Construction$1,979,000BRIDGE LOAN WITH CONSTRUCTION HOLDBACK
Austin & Smithville, Texas
A cross-collateralized bridge loan refinanced debt on an Austin mixed-use property and provided a $360,000 construction holdback for a residential project in Smithville. A nine-month interest reserve supported the financing structure.
Luxury Home Construction$1,634,000BRIDGE LOAN WITH CONSTRUCTION HOLDBACK
Kihei, Maui, Hawaii
A bridge loan with construction holdback financed 100% of a $1,092,000 construction budget to help complete a luxury single-family home already under construction. The borrower planned to finish and sell the property to repay the loan.
What is a commercial ground-up construction loan?+
A commercial ground-up construction loan provides financing for developing a new commercial property. Funds may cover eligible project costs, with disbursements typically made in stages as construction progresses.
What types of commercial projects may qualify?+
Eligible projects may include multifamily, mixed-use, industrial, retail, hospitality, and other qualifying commercial developments. Eligibility depends on the project, property location, and program requirements.
Can financing include land acquisition and construction costs?+
Potentially. Eligible transactions may include land acquisition and construction costs, depending on the project structure, budget, and financing program.
Are construction funds disbursed all at once?+
Construction financing typically uses a draw process, with funds disbursed in stages according to construction progress and the approved funding requirements.
What information should I prepare before applying?+
Helpful information includes the project location, land details, development plans, permit status, construction budget, timeline, builder experience, requested loan amount, and anticipated exit strategy. Available documentation may vary depending on the project's stage.
How important is the exit strategy?+
The exit strategy is an important part of evaluating a construction loan. Repayment may depend on selling the completed property, refinancing into longer-term financing, or holding the asset as an investment.
Does Myers Capital Hawaii work with mortgage brokers?+
Yes. Mortgage brokers can submit eligible construction opportunities for review and work directly with our team to discuss project requirements and potential financing structures.
Does Myers Capital Hawaii offer construction financing outside Hawaii?+
Yes. Myers Capital Hawaii lends in 42 states, subject to property, market, and program eligibility.
LET’S DISCUSS YOUR PROJECT
Ready to Discuss Your Commercial Construction Project?
Whether you're planning a new development or preparing a project for construction, Myers Capital Hawaii can help you explore financing options aligned with your budget, timeline, and investment objectives.
Share your project details with our team to discuss potential financing.
All financing is subject to underwriting, project review, applicable lending requirements, and program guidelines. Rates, terms, loan amounts, leverage, availability, and funding timelines may vary. This content does not constitute a commitment to lend.